

Hi fellow Sea Limited owners,
Big announcements
Forrest Li, founder and CEO of Sea Limited, published an internal letter to employees on 20 October 2026, filed here in an 8-K. The announcement was huge. Given its significance, it might have been better accompanied by a press release to shareholders. Nevertheless, the big news was:
Sea Limited is launching a cloud product-and-services platform called Sea Cloud. A B2B enterprise product, stepping out of Sea’s B2C comfort zone.
Sea Limited intends to IPO Monee to raise capital for growth.
Why now?
Sea Limited has built, tested, and scaled its localized, in-house cloud infrastructure for over a decade. Partnerships with Google, NVIDIA, and its in-house AI Lab, Sail AI Lab, show it was a question of when, not if, Sea would leverage its setup to offer cloud services. At the minimum, the success of Garena, Shopee, and Monee shows that Sea’s IT infrastructure (data center, applications, AI capabilities) works securely at scale and across borders. And whatever worked for Sea, it will work for its small-to medium-sized merchants and partners.
I remind you of the scale Sea is operating today:
~660M quarterly and 100M monthly active gamers on Garena.
~$160B annual GMV, 16B parcels processed per year (Q2’26 annualized) or 30M per day, on Shopee.
~$11B loan book ($1B off-book), 40M active credit users.
Forrest Li compared to when the company IPO in 2017:
Garena’s quarterly active users have grown almost 10 times, from 69 million to 666 million. Shopee’s quarterly GMV has grown 35 times, from $1.1 billion to $38.3 billion. And our quarterly revenue has grown more than 80 times, from $94 million to $7.8 billion.
All are the largest businesses in their respective category in Southeast Asia and Taiwan. In Brazil, it is just behind Mercado Libre and growing like wildfire. And profitably!
As a business owner, not just a shareholder, I am excited about what lies ahead.
As for a Monee IPO, the news is less significant, but it would give owners more clarity on how Monee manages risk while growing the region's largest digital bank. To date, I am impressed by the 1% non-performing loan ratio (with caveats, past reviews on Sea here), and I'd welcome more transparency on cohort performance, bad debt, and provisions.
Any concerns?
Sea Limited is considered capex-light and cost-conscious compared to peers such as Mercado Libre in Latin America, given how it runs and expands its logistics network (SPX Express). Shopee’s take rate has improved to ~14% over the past few years; however, its margin is razor-thin, at ~0.6% EBITDA/GMV. The market is concerned that all profit is already invested in free shipping, the VIP program, and fulfillment, so now adding cloud investments- when will it achieve the long-term 2.5% objective?
I understand. But my high-level thinking is:
Shopee’s razor-thin margin isn't the only source of funding for Sea Cloud; we also have a highly profitable, evergreen Garena gaming platform and a highly profitable Monee digital banking segment. Together, the current run rate is ~$4B annualized cash flow, available for reinvestment.
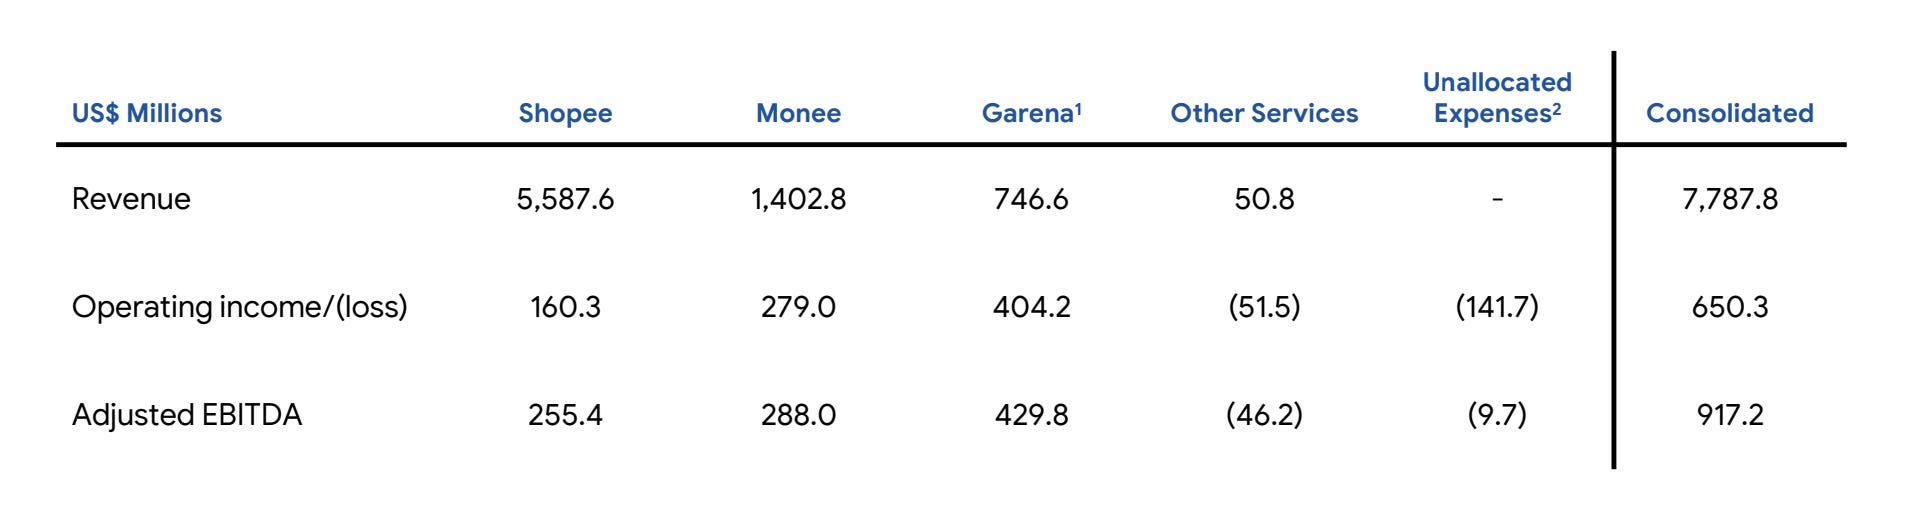
Additionally, Shopee's investments focus on generating purchase-behavior data and improving unit economics through scale.
These are hard-to-copy proprietary ingredients for producing superior customer value (lower costs, faster and more reliable delivery, faster refunds, better VIP members’ offers, more relevant ads, higher ROI ads to merchants) and, as a result, higher-margin adjacent businesses (advertising, VIP membership program, lower customer acquisition costs for Monee, better risk-adjusted loans, etc.).
Now expanding the internally developed cloud applications to external clients could mean a prolonged period of razor-thin margins. Given the high costs of advanced CPUs, GPUs, high-bandwidth memory, energy bottlenecks, and the diminishing returns of Moore’s Law, Sea’s ~$4B free cash flow and $5B cash pile could disappear quickly.
Well, it depends.
Sea has already invested in 40+ data centers with 25K GPU cards and a 100MW+ workload around the world. That’s equivalent to a small-to-medium-sized neocloud provider’s capacity.
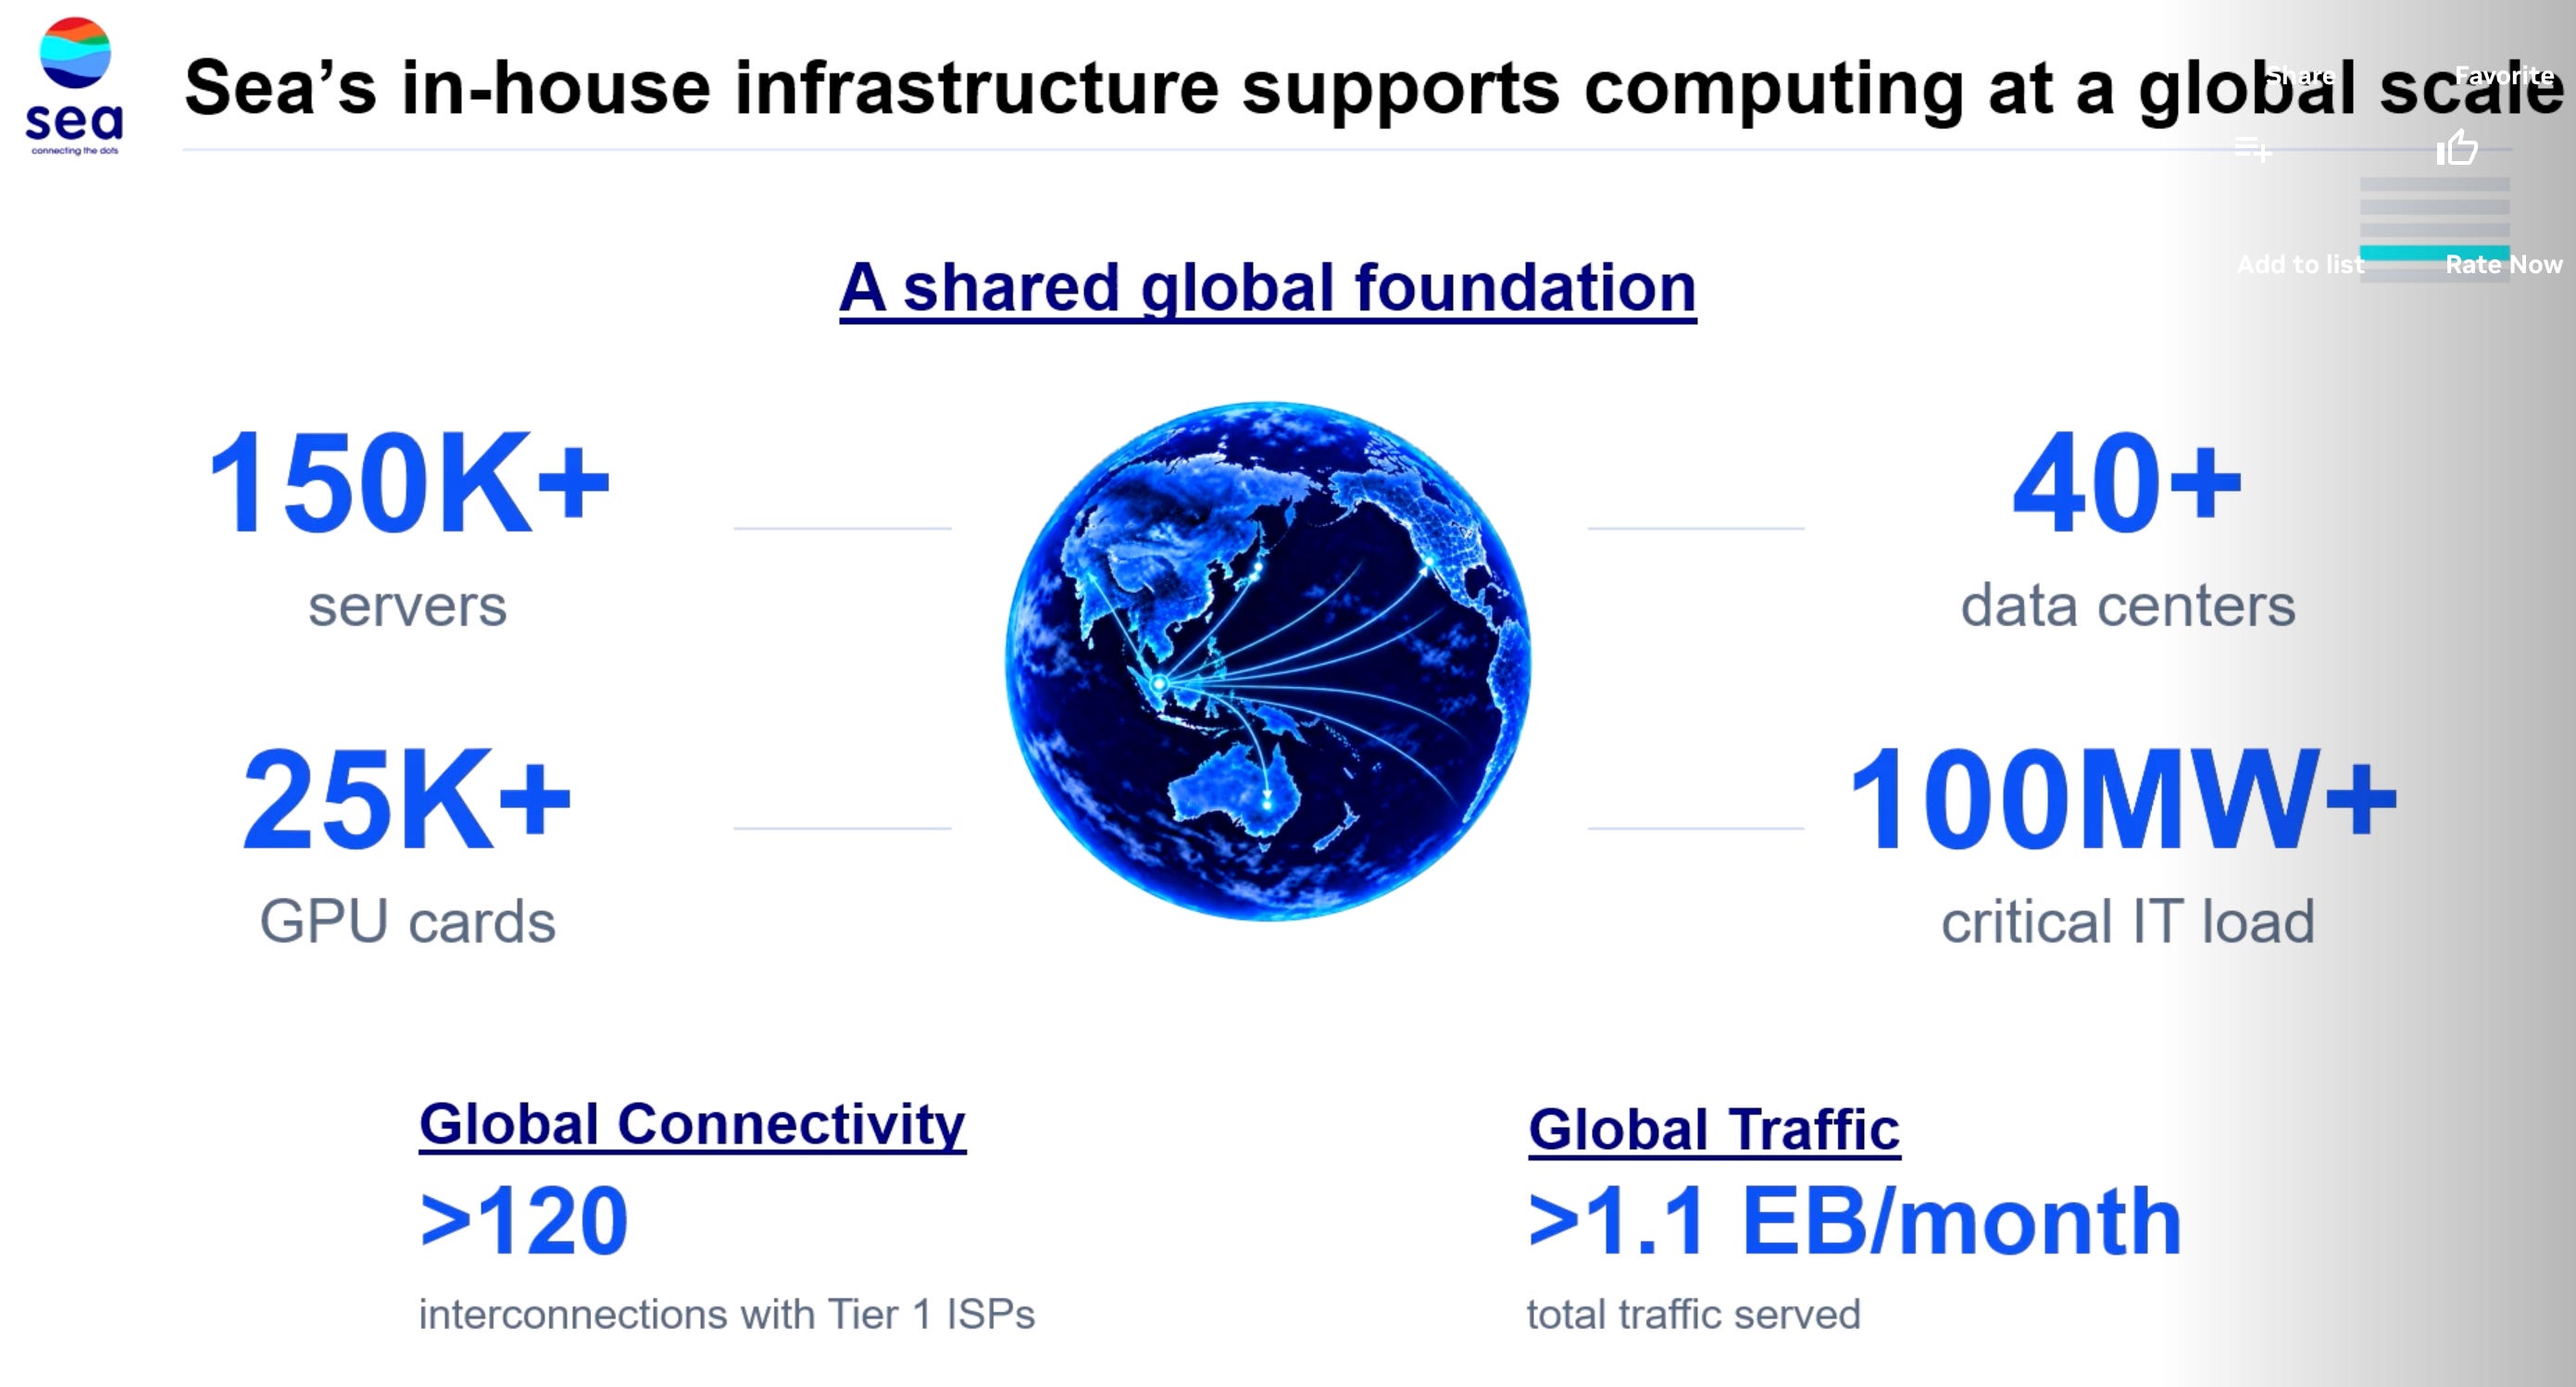
If it goes the neocloud direction, we can expect a heavy capex path. But if Sea does what Forrest Li is implying in the letter and the 5 layers AI has embedded in Sea’s operation, see next, the outcome will be very different.
"Sea Cloud will be an AI-first enterprise platform, built by a team that has spent a decade running infrastructure at enormous scale, under real commercial pressure, for some of the most demanding consumer businesses in this region.”
Over the last two years, around 500 Sailors have been rebuilding that platform to power something new: the wave of AI applications rising across every part of Sea.
- Letter 20 Oct 2026
The 5 layers of AI that have been embedded in Sea.
The next section is for paid readers. If you are new to SWI, check out our FAQ and Owner Manual. Expect SWI#25 coming very soon.
a monopoly in most advanced and highest growing market, SaaS-like margins, consistent high ROIC, a long runway for reinvestment, and, importantly, at a reasonable valuation.
The Sleep Well Portfolio consists of time-tested, market-leading companies. We screen them with a rigorous checklist and regularly track their theses to determine when to buy. So far, we have made one mistake, but are happy with the current 13 holdings. All about us here.