

The Sleep Well Portfolio consists of time-tested, market-leading companies. We screen them with a rigorous checklist and regularly track their theses to determine when to buy. So far, we have made one mistake, but are happy with the current 13 holdings. All about us here.
Hi all,
I spent the last few months searching for direct AI-beneficiary businesses. But I didn’t want one that would require my daughters or me to guess which frontier model or leading-edge chips would win in the future. That business would also have to be capital-light, less cyclical than peers, and meet many of the criteria I look for in a ‘sleep well’ at night business. In other words, I wanted another ‘The VAT Group ’- Sleep Well pick #2.

So, in the coming week, you can expect a business with
a monopolistic market share, high margins, consistent high ROIC, a long runway for reinvestment, and, importantly, a reasonable valuation.
I intend to trim one position to buy this business.
August saw some very good Q2 earnings; I’ll leave the review here so you don’t get rattled by the stock-price whipsaw from rising yields or ~$90 oil prices. Most of the stock-price drivers between quarterly earnings are just emotion, not real business change.


Veeva Systems, Fortinet, and CrowdStrike also reported very good Q2 earnings, and I made brief comments in the August portfolio review.
CrowdStrike - Security of AI
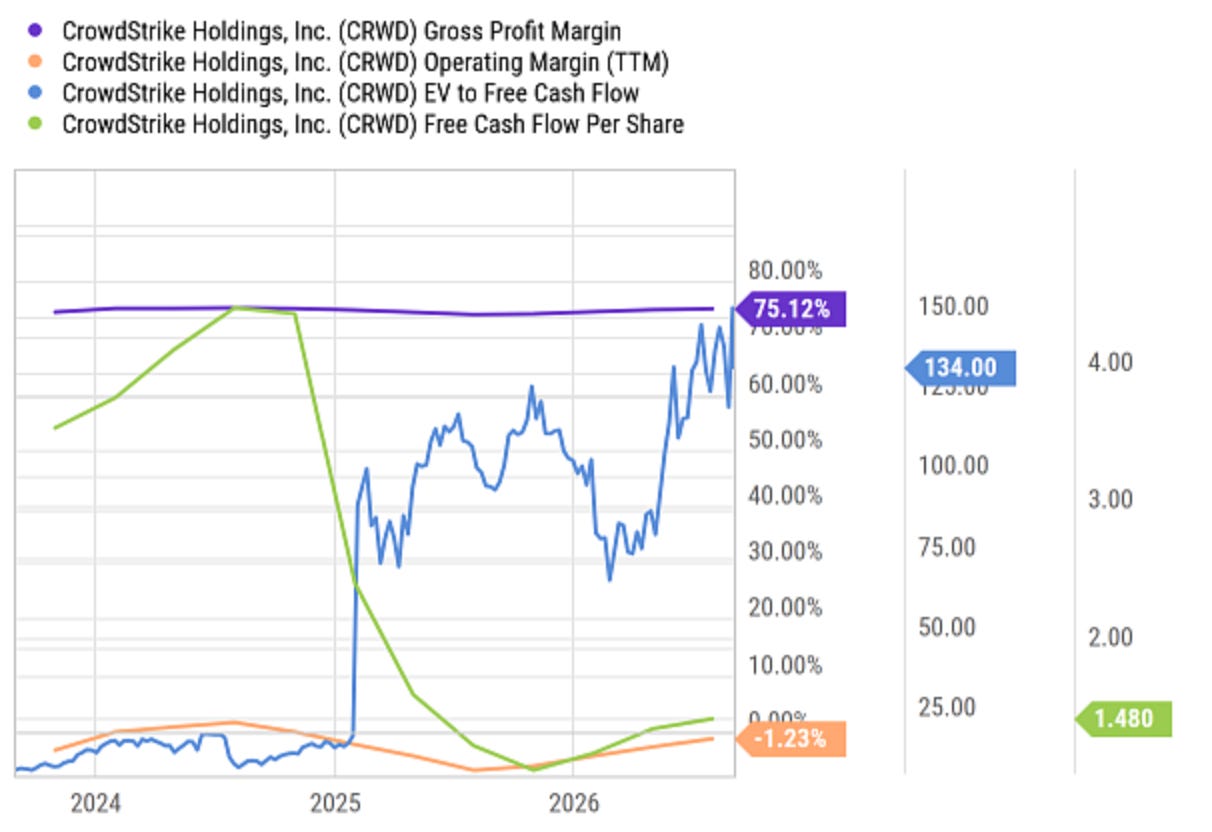
At the August review, I commented that CrowdStrike is a candidate for a trim, given the high expectations baked into its 140x free cash flow valuation and $270B market cap.
At ~$6B ARR, CrowdStrike aims to reach $20B ARR by 2035, a near 4x in 9 years or a 15% CAGR. However, even with a very optimistic 40x FCF multiple, it still doesn’t make sense to price the stock at $270B today.
Quick math: Free cash flow by 2035: $7B (35% margin of $20B) x 40x = $280B market cap.
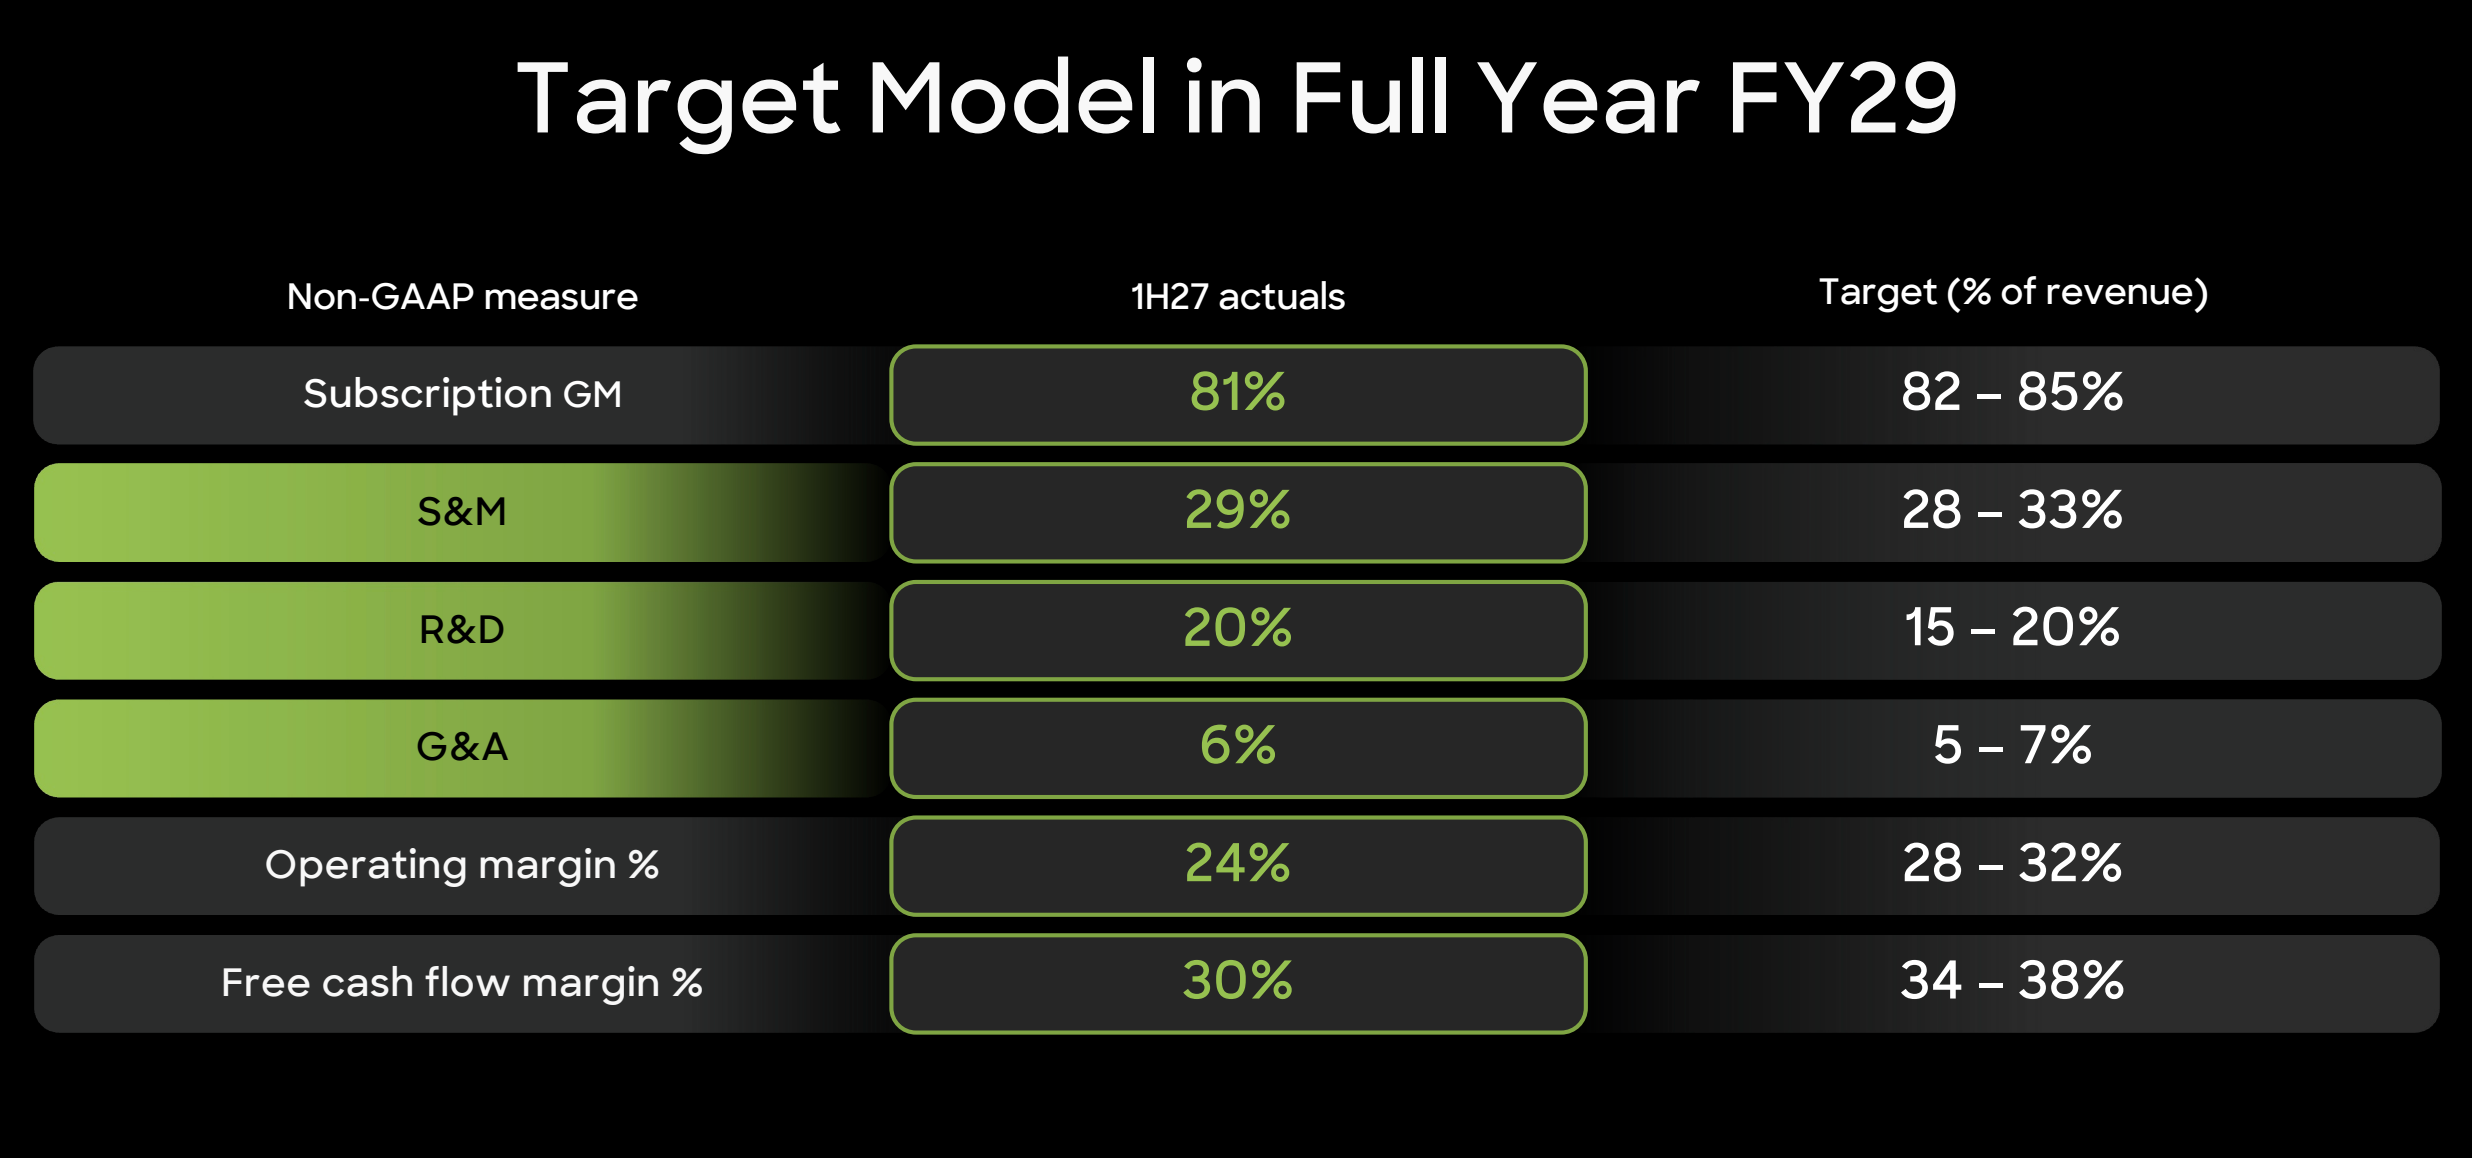
What if CrowdStrike grows ARR by 20% CAGR? That makes ending ARR at $30B, ending free cash flow at ~$10B, and a market cap at ~$400B. But that assumes:
CrowdStrike’s total addressable market (TAM) to grow just as fast (20%), to $500B from the current estimated $149B, much higher than management's current estimate of ~$325B.
CrowdStrike successfully cross-sells to non-endpoint modules
CrowdStrike successfully moves downstream to smaller companies
Microsoft’s Defender and Palo Alto Networks are not putting up a fight
All fairly unlikely; I expect a price war or value bundles from Microsoft and at least a few unforced errors along the way (recall the Jun 2025 global IT glitch caused by CrowdStrike).
That said, AI development is unprecedented, a risk to humanity, and the clearest tailwind for companies like CrowdStrike. Watch OpenAI’s CEO’s speech at the UN council for yourself.
AI threats have become more real-time, more frequent, and cheaper to spread. Instead of coming from hackers and nation-states, it’s now from swarms of ‘agents’.
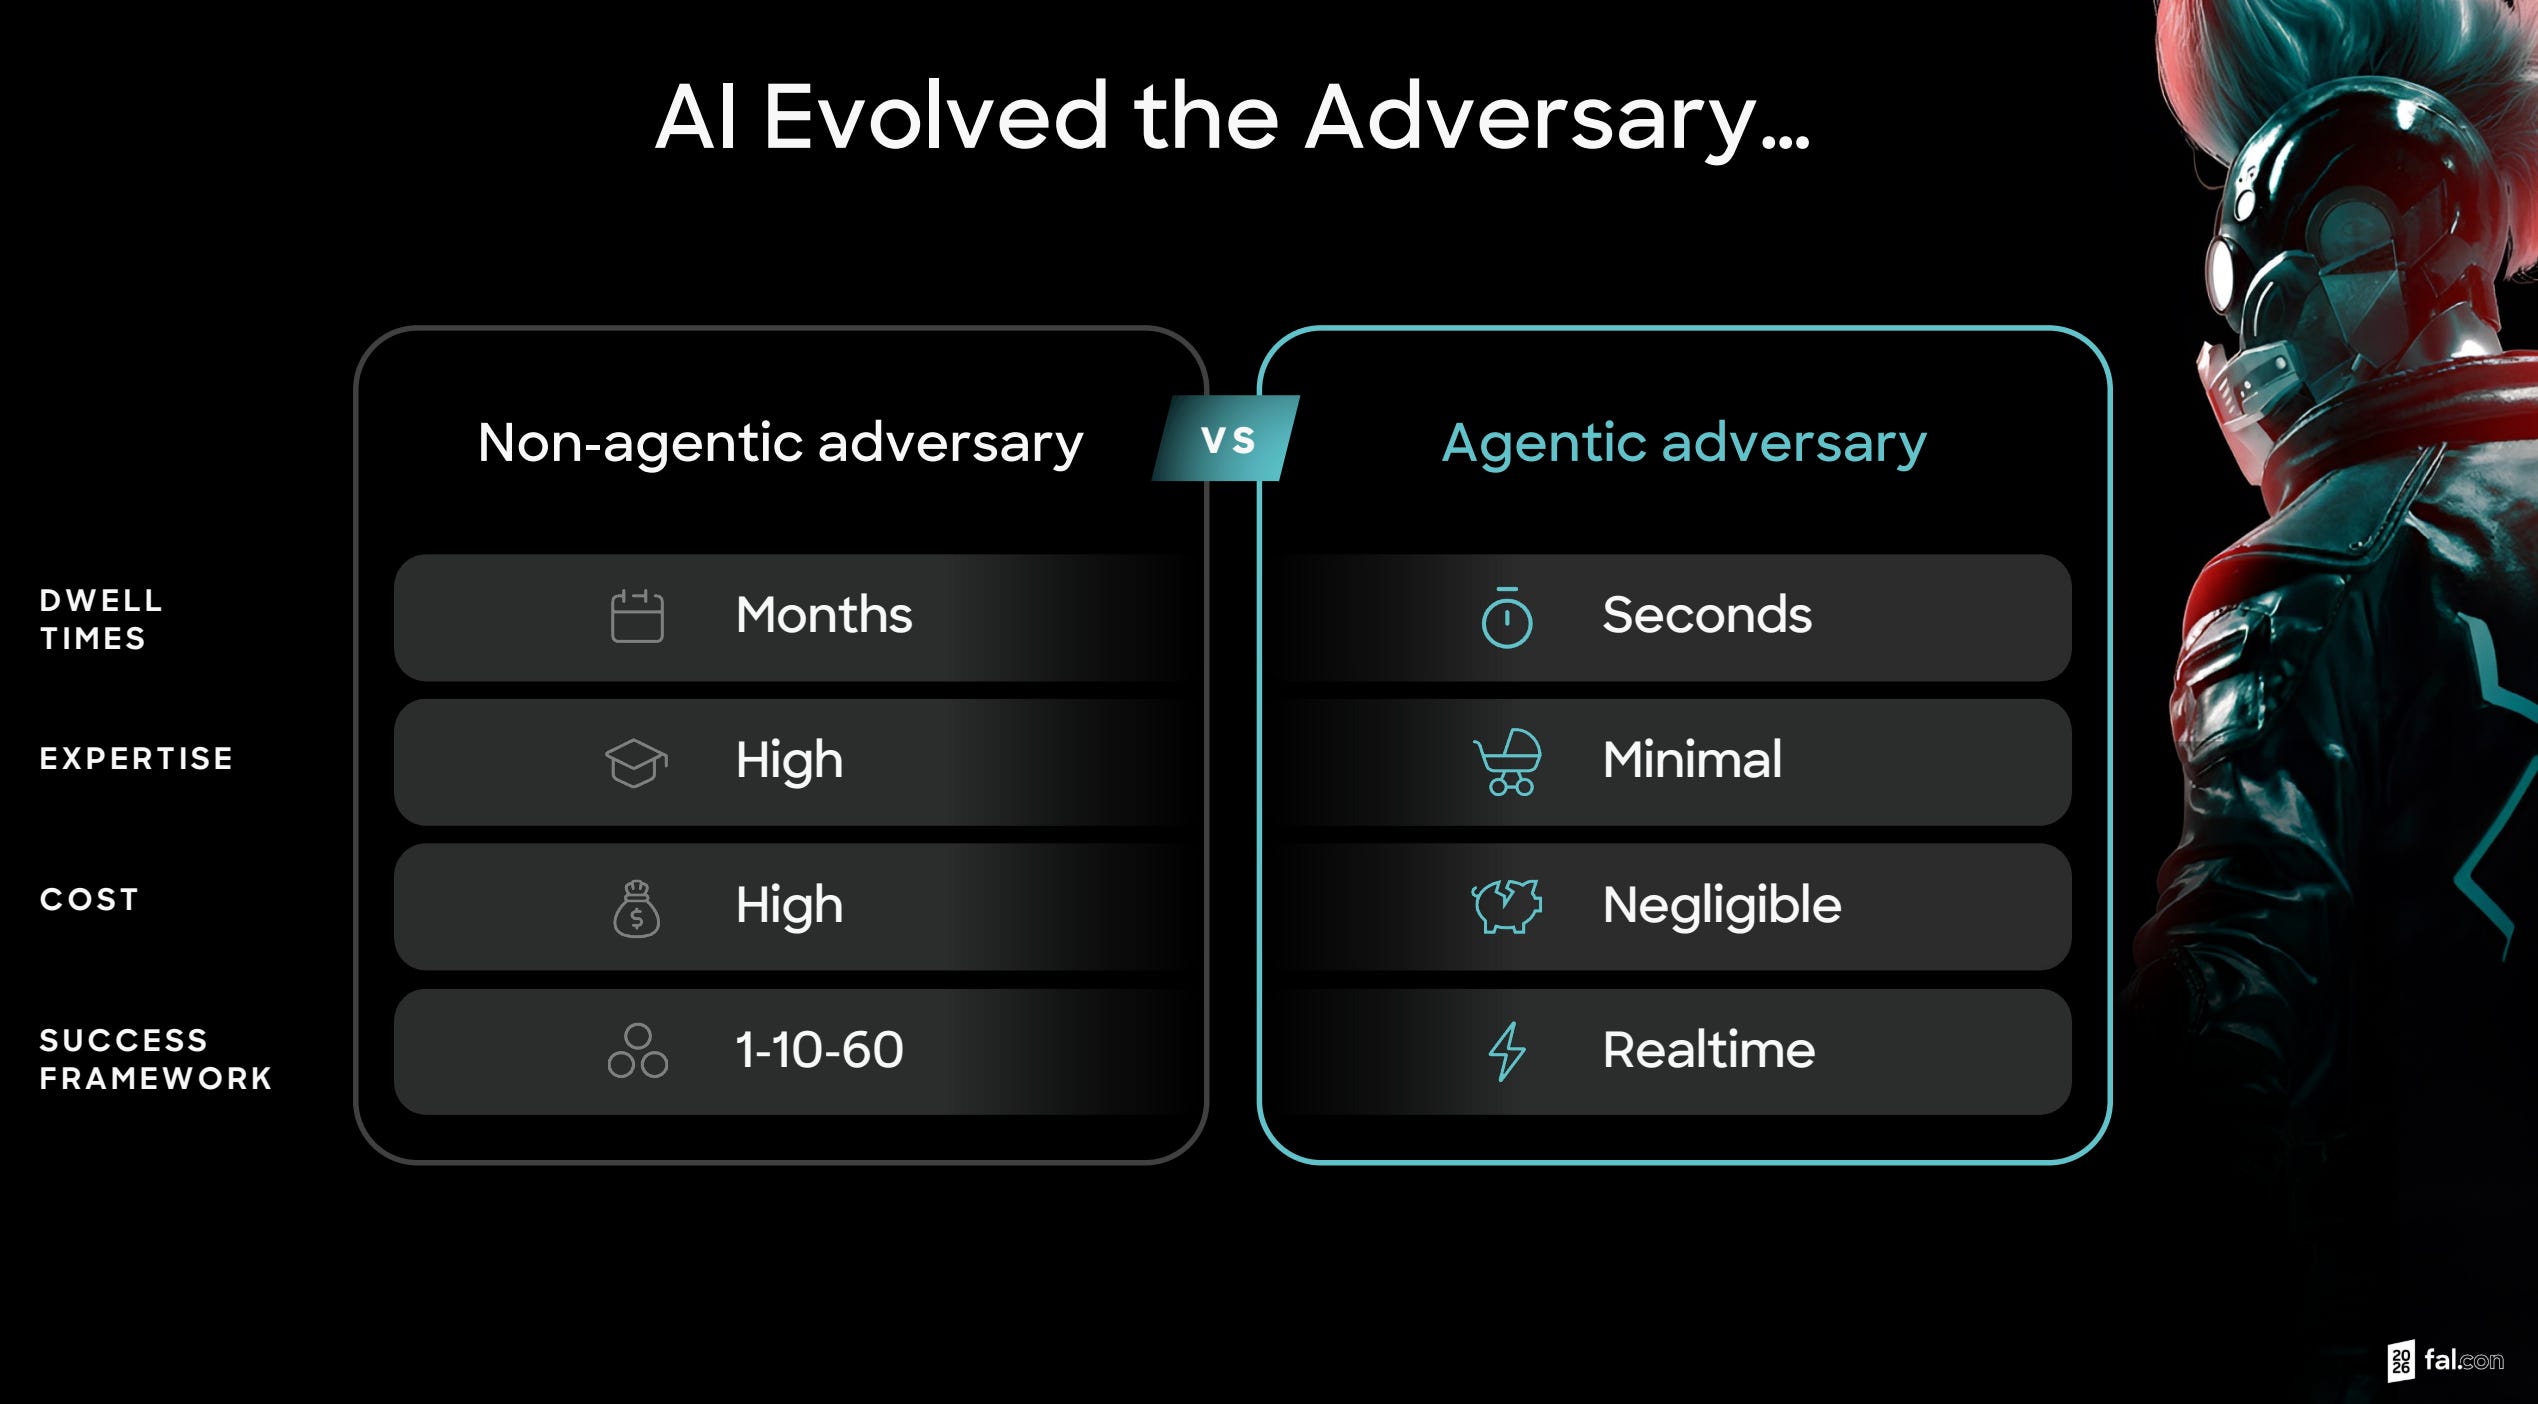
Read Anthropic’s letter, and even OpenAI is calling for urgency and collective effort on cyber defense.
We have a limited window to strengthen cyber defenses.
Calling every organization.
Make cyber defense an immediate leadership priority.
- letter (sept 2026)
Hence, I could very well regret trimming the CrowdStrike position here.
“What we’re hearing from customers is they want to deploy more AI, but they’re being held back because of security, compliance, privacy, data protection type issues.” - CrowdStrike CEO George Kurtz
Portfolio summary of Sept 2026
Here is how the portfolio looks today:
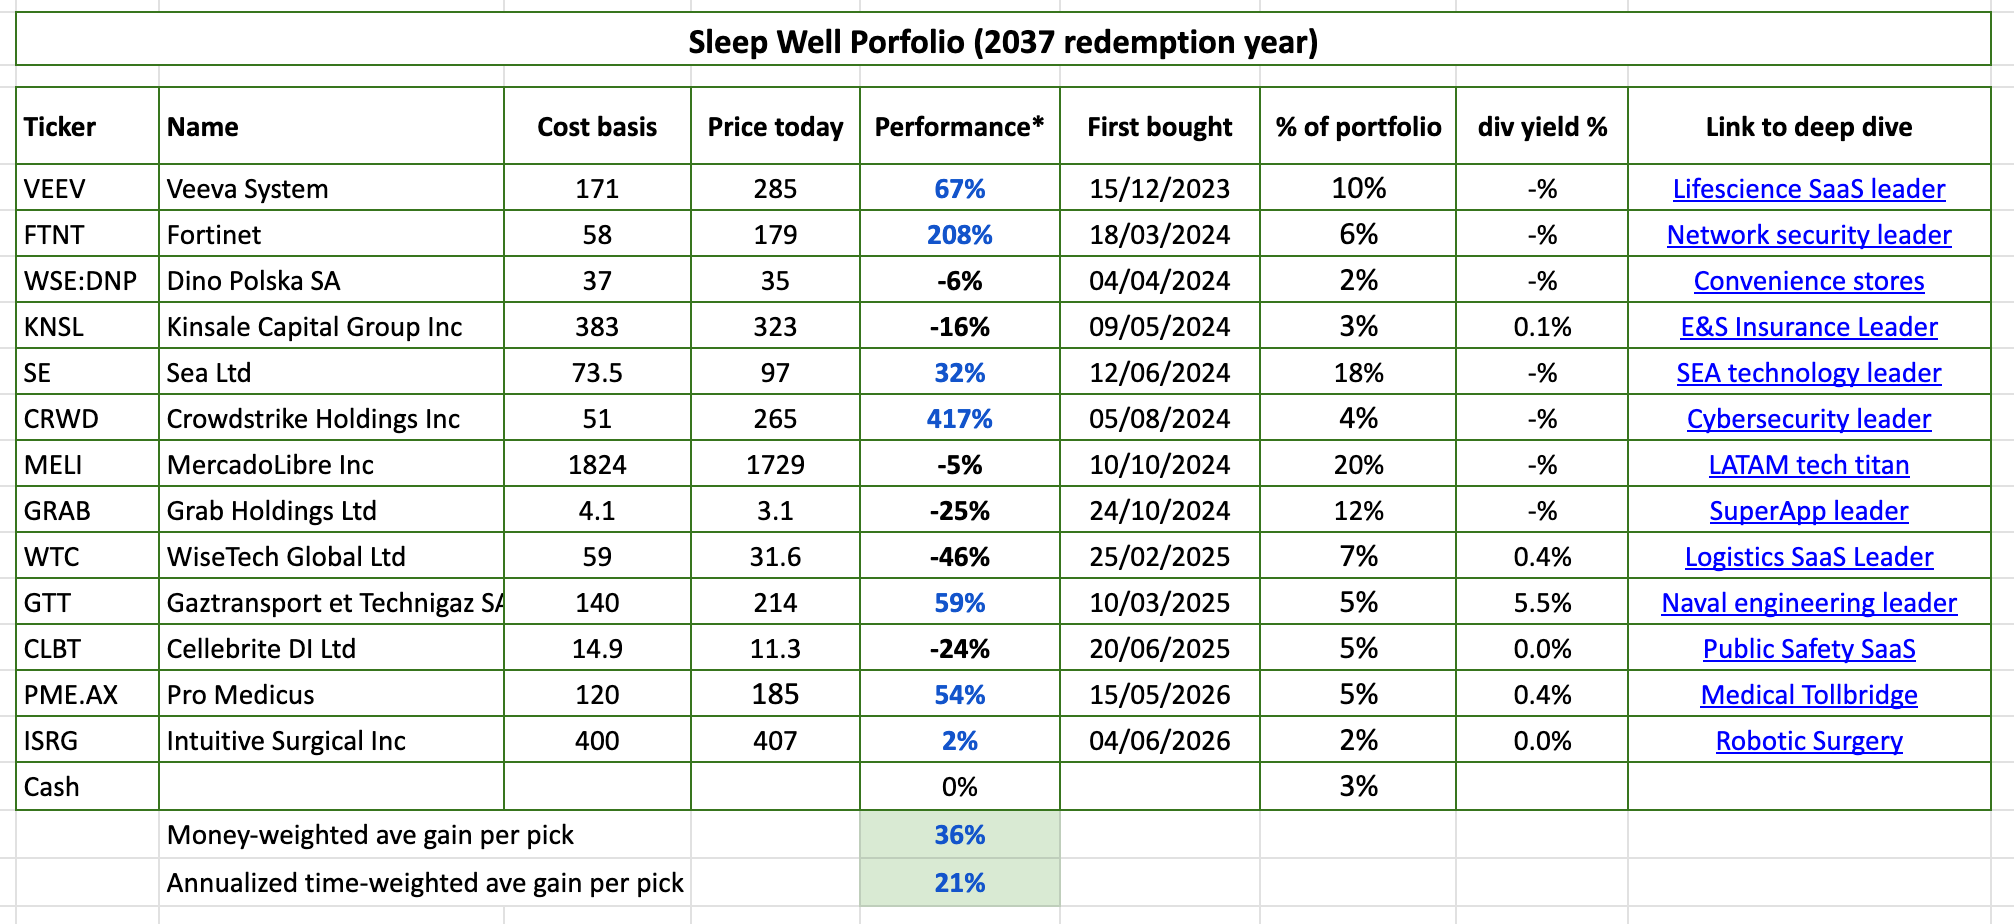
After 10 months of ‘looking wrong’, the last three months are starting to prove that the hardest thing in investing is actually the waiting, and even harder is slowly buying when everyone is selling. No one quite knows when the bottom hits, but you have to know what is a reasonable deal for you personally, i.e., what is your financial goal, what is enough, what is the risk, how long can you wait, how confident are you about the value of the business you are buying, etc.
As always, time will tell. I have survived the 2008, 2015, 2020, 2022, and 2025 down years. Market cycles are a feature of long-term investing, not a bug.
By 2037 (when my daughters will have full control of the Sleep Well Portfolio), none of this would matter. I continue to put aside some savings for them and own more winners - ‘winner keeps winning ’- in both bear and bull markets.
If you are new to SWI, check out our FAQ and Owner Manual.
If you are already an annual member, you can access the Sleep Well Portfolio and Thesis Tracker via the link below.
